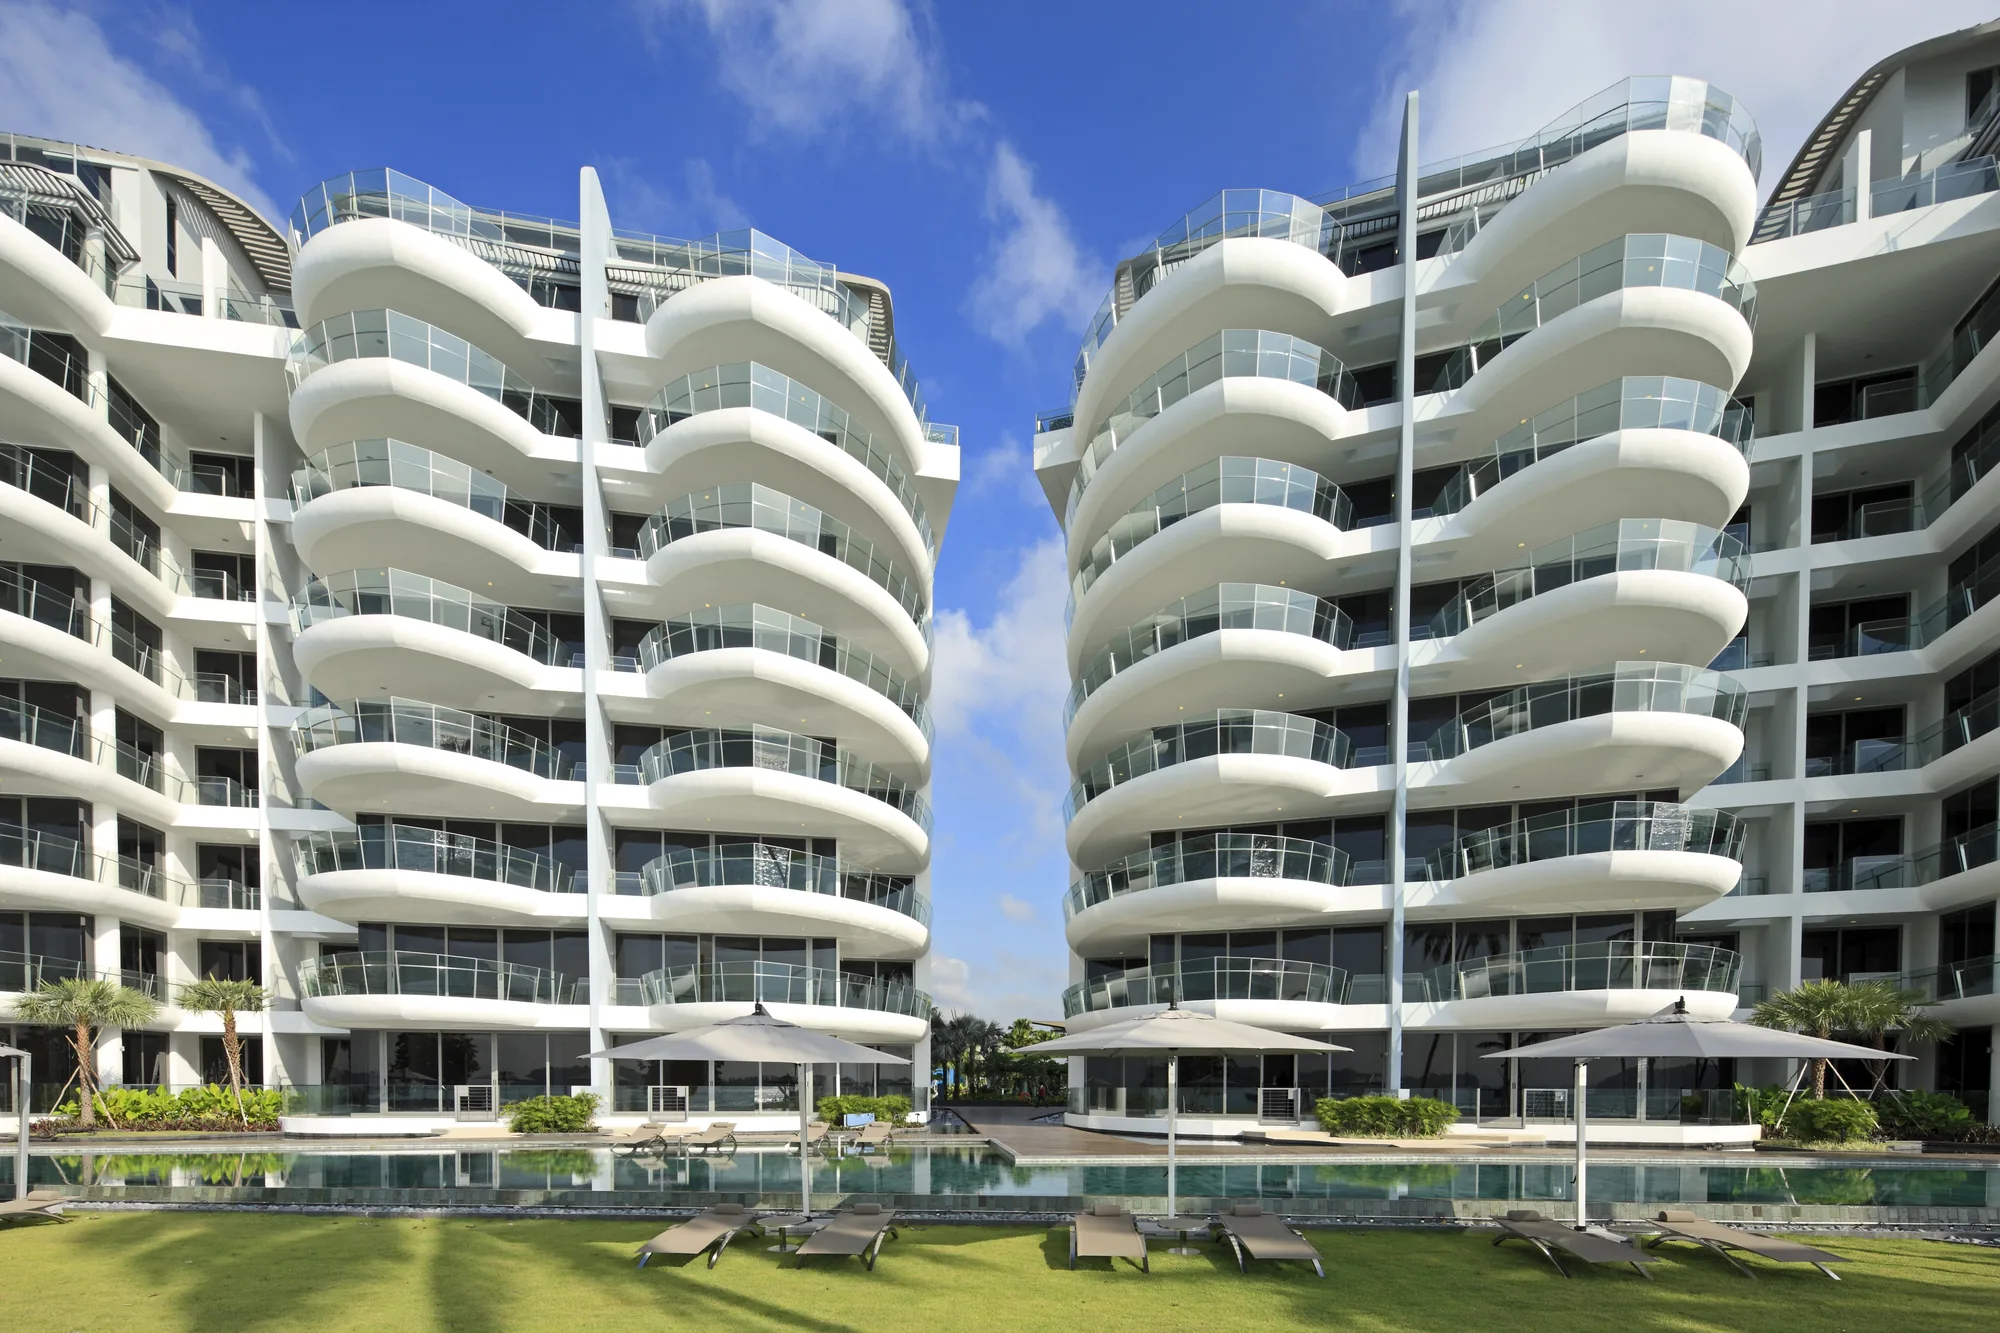
 Photograph
A Seascape Purchase Runs on a Completed-Home Timetable
Buying a home at Seascape follows the timetable of a finished building: an option to purchase secured with a booking fee, the sale and purchase agreement signed within the option period, stamp duty paid within 14 days of signing, and legal completion, when the loan is drawn in full and the keys are handed over. Because the Temporary Occupation Permit was issued on 25 February 2011, nothing waits on construction.
The sale terms depend on the seller and are set out in the option to purchase; ask for them in writing before committing. The precise amounts and deadlines for any one home appear in its own option and agreement, and the Sales Concierge sends the sale terms for Seascape together with the price list.
In short, the path runs from option to agreement to completion, and each step falls on a date the option or the agreement sets. The sections below take them in order and show where the booking fee, the stamp duty, the loan and CPF savings fit.
Step One at Seascape: the Option to Purchase
The option reserves a chosen home against a booking fee. The amount of that fee is one of the terms the option to purchase sets out.
The option stays open for the period it states. That window is the time to settle financing, confirm the stamp duty and let a lawyer review the documents.
The booking fee is part of the price, not an extra charge, and it counts towards the cash share that MAS requires. Ideally, before paying it, a buyer will have seen the home, read the plans and obtained a bank’s in-principle approval, so that the option period that follows can be spent on the legal review rather than on financing.
Step Two: the Seascape Sale Agreement and Stamp Duty
The sale and purchase agreement is signed within the option period, on the terms the option sets out. Signing starts the stamp duty clock: Buyer’s Stamp Duty and any Additional Buyer’s Stamp Duty are paid to IRAS within 14 days.
| Step | What happens | Timing |
|---|---|---|
| Option to purchase | Booking fee, as the option sets out, reserves the home | On choosing the home |
| Sale and purchase agreement | Signed on the terms the option sets out | Within the option period |
| Stamp duty | BSD and any ABSD paid to IRAS | Within 14 days of signing |
| Legal completion | Balance paid from the loan, CPF and cash; keys handed over | As the agreement sets out |
Source: IRAS for stamp duty, read on 30 October 2026. The sale terms depend on the seller and are set out in the option to purchase; the documents for a particular home govern.
The article on who can buy and the stamp duty that applies sets out the rates by buyer profile.
Step Three: Seascape Loan, CPF and Legal Completion
With the building complete, the remaining sums fall due within weeks of signing rather than over years. They are met from three sources: a bank loan, CPF savings and cash. The bank releases the entire loan on the day of legal completion, with the first monthly instalment due a month later.
MAS rules set the frame. On a first housing loan the standard loan-to-value limit is 75%, with at least 5% of the price paid in cash; a second loan is limited to 45% and a third or later to 35%, each with a minimum cash share of 25%. A tenure beyond 30 years, or a loan running past the borrower’s 65th birthday, moves the loan to the lower limits of 55%, 25% or 15%.
The Total Debt Servicing Ratio caps all monthly debt repayments at 55% of gross monthly income, with the new loan tested at 4% or at its thereafter rate if that is higher, and loans on private homes can run for up to 35 years. With about 79 years left on the lease, CPF savings can be used in full by any adult buyer within CPF Board’s limits. The TDSR calculator estimates the loan an income supports and the housing loan page sets out each rule.
What Buying Completed Means in Practice at Seascape
Buying a finished home removes several unknowns. The rooms can be measured, the finishes inspected and the view checked at the hour of the day that matters most to the buyer. The facilities are already in use, and the condition of the grounds can be seen rather than imagined.
It also concentrates the payments, which fall within weeks: the booking fee, then the stamp duty, then the balance at legal completion. On a first loan at the standard limit, the bank lends up to 75% of the price, at least 5% is paid in cash, and the remaining 20% can come from cash or CPF savings, as the housing loan page explains.
The upside of that concentration is speed. A buyer can move from a viewing to living at Seascape within a matter of weeks, with the timing fixed in the agreement.
Preparing to Buy at Seascape
Three things shorten the process. An in-principle approval from a bank turns the loan into a firm figure before a viewing; a stamp duty estimate for the buyer’s profile fixes the cash needed within 14 days of signing; and a shortlist drawn from the floor plans lets the Sales Concierge confirm which homes are still open for selection.
Seascape is completed and open for sale, so a viewing shows the actual home, its finishes and its outlook rather than a model. Showflat viewings are arranged by appointment through the Sales Concierge. The price list and the sale terms are sent on request.
General information only, as at October 2026: the option, the agreement and the bank’s letter of offer for a particular home govern.
General information as at the date shown, not financial, legal or tax advice. Seascape particulars are taken from the developer’s fact sheet, brochure and plans; statutory rules repeat this site’s financing pages and the agencies named. Sources: IRAS, MAS and CPF Board, as set out on this site’s TDSR calculator, stamp duty and housing loan pages.
Ask the Sales Concierge about Seascape
The Sales Concierge sends the price list on request, the homes still open for selection and the e-brochure for Seascape. Showflat viewings are arranged by appointment through the Sales Concierge.